
Advertising Disclosure: Links and credit card offers on this page may earn us a small commission. They never influence what we cover but they do keep the lights on. Learn More
Updated to reflect that Pay1040 decreased their fee from 1.85% to 1.75%. ACI is 1.85%. PayUSATax is no longer listed on the IRS website. Note that business cards incur a higher fee.
In this article
Should you pay taxes with a credit card?
There is one credit card that I would pay my taxes on (and advise you to) without blinking an eye.
📰 Want MilesTalk to show up in your Google News? (Yes, you do!).
👉 Click here to add MilesTalk as a trusted news source for all things related to miles, points, and credit card rewards in your Google searches!
What in the world is Dave on about? There are FEES when you pay taxes with a credit card!!!!
That’s true.
But hear me out. And first, I must clarify that for everything I’m going to write in this article, I am making the assumption that you have the funds to simply mail the IRS a check and would prefer to pay, effectively, less if you could. If you cannot repay the credit card in full when the statement is due, then do not continue reading. Consult your tax advisor or financial planner in that case.
The “can’t lose” profit paying taxes
You can pay tax using a credit card with a 1.75% fee at Pay1040. With the Citi Double Cash® Card, you earn 2% cash back (1% when you spend and 1% when you pay the bill).
So, you will profit 0.25% no matter what. The absolute worst case is that for a $10,000 tax bill, you make $25.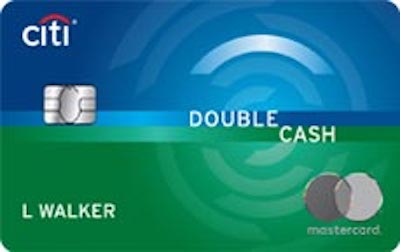
I know, that doesn’t sound like much – and it’s not – but it’s the optionality of the Citi Double Cash credit card when combined with a Citi Strata Premier® Card or Prestige card that makes this so appealing. The unique ability of the Citi Double Cash to earn 2% in cash back off the bat with the option to convert those, 1 to 1, to Citi ThankYou points later is what makes this so attractive.
I wrote this article last year about the Citi Trifecta (or even Quadfecta). It discusses how you can earn 2% cash on the Double Cash but then opt to convert to ThankYou points later.
Note: While Double Cash is the “pure play” with optionality for cash or points, the Capital One Venture Rewards Credit Card, Venture X, and Bilt Palladium Card all earn 2X points on spend and also work in this scenario – you just cannot optionally cash out for cash at 1 cent per point as I describe below. Also, IMPORTANTLY, Bilt Palladium explicitly states you won’t earn ANY points on tax payments. This applies to all Bilt credit cards v2.0.
Cash Now or Points Later
This is so key right now. If we aren’t “back to normal” in 3-6 months, you may want the cash. If you paid $50,000 in tax liabilities, you paid $875 in fees and earned $1,000 in cash back. You’re net positive $125. That’s not nothing!
You have $1,000 in your cash back account which you can get deposited straight into your bank account, but there’s no rush.
Maybe in a year you want to book a round trip from New York (Newark) to Los Angeles in Business Class. If you can find the award space, you could book that for just 25,000 Turkish miles (total, round trip). Those miles can be transferred 1:1 from ThankYou points.
So, you transfer $250 worth of points into ThankYou points, becoming 25,000 ThankYou points. You transfer those to Turkish and book your flights. (Note: there is a delay of 1-2 days to transfer ThankYou to Turkish so in reality you’d probably want to transfer once you had a hunch you could find flights that worked).
You just got a flight worth $800 ++ and have $750 left over from your $1,000.
You aren’t buying points – you’re acquiring optionality on them.
That’s my stock market brain comparing this idea to buying options, although in this case you are being paid 0.25% to TAKE them.
You don’t have to pay a premium like you would for a stock option. Even if you didn’t have (or keep) a Citi Strata Premier® or Prestige to be able to transfer down the road, your worst case is a 0.18% gain.
That’s very different from, for example, putting your taxes on a Chase Ultimate Rewards card like a Chase Freedom Unlimited®. Those points are worth 1.5% cashback and then if you combine with a Sapphire card, you can get 1.25 – 1.5 cents a point on travel. So, combined with a Chase Sapphire Reserve®, you are getting 2.25% in travel value – but ONLY if you have a Sapphire (or an Chase Ink Business Preferred® Credit Card), else you could only cash out for 1.5% and you’d lose 0.46% on the whole thing.
That’s not to say that if you are ready to book travel it’s not a good deal, but who is booking travel right now??
The more tax you owe, the more it makes sense.
Other Options:
If you don’t have or can’t have a Citi Double Cash, there are other cards that pay you 2% cash back and still beats that 1.75% fee.
The Fidelity Rewards Visa Signature, for example, earns the same 2% as the Citi Double Cash, just without the option to use as transferrable points.
And the American Express Blue Business Cash® Card earns 2% cash back on up to $50,000 in purchases per year.
If you like American Express Membership Rewards points which I value at 1.7 cents each, consider The Blue Business® Plus Credit Card from American Express, which earns 2X points on eligible purchases up to $50,000 each calendar year. Even if you only get 1.5 cents in value from them, that’s a 3% return for 1.75% in fees – or a 1.25% gain.
What about signup bonuses?
The more advanced among you will know there are two other considerations when deciding on paying to use a credit card to pay taxes.
If you are trying to meet minimum spend for a signup bonus, this a super easy way to do so. If you just opened a Chase Ink Business Preferred, for instance, you’ll need to spend $8,000 within 3 months for your 100,000 point bonus. If you will spend $5,000 naturally in the three months, you could charge $3,000 (paying $175) and get the 100,000 points worth at least $1,250 in travel. Not a bad deal at all. Note that processors have started charging higher fees for business credit cards, although it’s often possible to add the card to your PayPal wallet and use that to pay at the standard fee rate.
That means it’s probably also a good time to check out the best current credit card signup bonuses.
The same rule about paying your bill off in full still applies here.
Could Plastiq be a better deal?
For those unfamiliar with Plastiq, it’s a service by which you can pay a bill with a credit card for a 2.9% fee.
It’s often and primarily used in our world either to 1) meet minimum spend on a new card organically (i.e. rent is your biggest expense but they don’t take cards), or 2) when you have a card that earns more than the fee.
There’s no reason to pay tax with Plastiq when you could pay 1.75% directly, except that they will sometimes email promos for reduced fees of 1% or 1.5% (or other promotional variants). So it wouldn’t hurt to signup at Plastiq and see if you get a promo.
When you refer people to Plastiq you may also earn Fee Free Dollars to use towards future payments, so if you have saved some up, keep taxes in mind as a potential way to spend them – ideally to hit that new card bonus spend. The referral program changes frequently and it’s possible there is none at this time.
Bottom Line on Paying Your Taxes with a Credit Card
It only makes sense if you lock in a profit, either via signup bonus or more cash back (not just points) than you are paying in fees. Above, I’ve given you scenarios in which the juice is undoubtedly worth the squeeze.
Do you pay taxes with a credit card?
Let me know below in the comments, on Twitter, or in the private MilesTalk Facebook group. And don't forget to follow me on Instagram for all sorts of tips on miles, points, credit cards, and travel.
If this post helped you, please consider sharing it!
You can find credit cards that best match your spending habits and bonus categories at Your Best Credit Cards.
New to all of this? My “introduction to miles and points” book, MilesTalk: Live Your Wildest Travel Dreams Using Miles and Points is available on Amazon and at major booksellers.
Best tip I learned in 2022 was paying my taxes via PayPal using a credit card through the Bill Payment feature. No fees! I’ve done this 2 years in a row.
That’s a great tip! Which taxes were these? Local state income tax? I am pretty sure there’s no way to do this for federal?
Ah yes, I guess I was overlooking the fact this article was about federal or state taxes. The taxes I paid were real estate and personal property taxes. Still a win since these added up to thousands of dollars so keep this idea in mind for local taxes.